
2021 Challenger Bank Outlook: Growth, Models, and Risks
Challenger banks achieved growth in both users and funding in 2020, but their business models rely on interchange fees, facing risks of valuation corrections in 2021. Industry experts predict that product diversification, subscription models, and niche markets will become new directions.
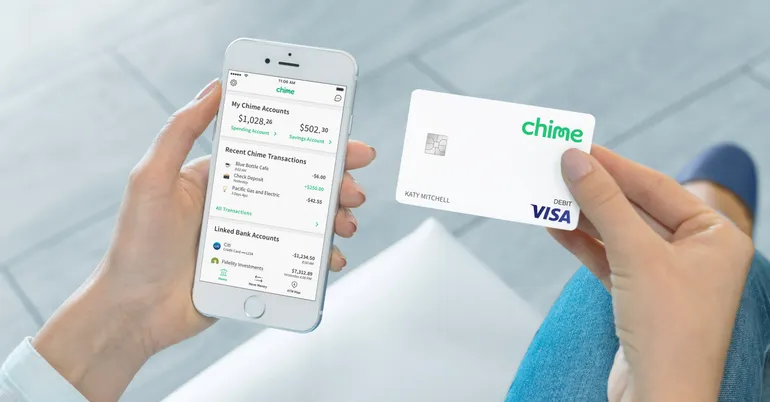
Over the past few years, challenger banks have grown rapidly. These digital banking institutions, many of which claim to aim to disrupt traditional banking, have brought more attention to the fintech sector through large funding rounds and steady growth in user numbers.
According to data compiled by Exton Consulting, as of December 2020, there were 256 neobanks worldwide, and many reported steady account growth over the previous 12 months.
Chime completed a funding round in September 2020, reaching a valuation of $14.5 billion; according to Bloomberg, the company had 8 million users in February 2020, up from 1 million in 2018. Varo became the first challenger bank to obtain a U.S. national bank charter in July 2020, and according to Reuters, its customer base doubled in 2020, approaching 2 million accounts. Challenger bank Current grew its user base from 1 million in June 2020 to over 2 million by November, and completed a $131 million Series C round in November, with a valuation of approximately $750 million.
As the challenger bank market continues to attract venture capital, new users, and even celebrity endorsements, can the momentum of this new banking model extend into 2021?
Filling the expectation gap
Challenger banks have achieved user growth because they can offer financial services that some large traditional banks lack. Lane Martin, banking partner at consulting firm Capco, said: "These challenger banks emerged because they can fill the expectation gap between the current state of banking and what it should be. They prove their value by addressing unmet needs and quickly providing logically clear services."
Challenger banks like Chime and Current attract the market living paycheck to paycheck with features such as no account maintenance fees and overdraft protection—a market that may not have received tailored services from traditional institutions. A 2018 Federal Reserve study (released in 2019) found that 40% of Americans would struggle to come up with $400 for an unexpected expense. Challenger banks claim that large banks like JPMorgan Chase and Bank of America do not adequately address this financial fragility through their products and services.
Adam Hadi, VP of Marketing at Current, told Banking Dive last year: "Our business is fundamentally different. We don't rely on deposit scale to make money, unlike traditional banks... Banks always show up when you have a lot of money. When you have no money, which banks serve you?"
The vast majority of challenger banks profit through interchange fees. Banks charge merchants interchange fees when customers use their debit cards for purchases. Although the interchange fee percentage challenger banks can charge is small, it is higher than what larger bank competitors are allowed to charge. Under the Durbin Amendment in the Dodd-Frank Act, banks with assets below $10 billion can charge merchants up to 1.5% per debit card transaction. According to Fortune analysis, this is seven times higher than what traditional banks like Wells Fargo or Citi can charge.
Although the interchange fee model allows startups to establish themselves in a saturated market and leverage advantages that some industry giants cannot enjoy, not everyone believes challenger banks can maintain momentum in 2021. So far in 2021, digital banks Azlo and Simple, as well as Aura, an alternative lender targeting Latinos, have shut down.
Nathaniel Harley, co-founder and CEO of online account opening platform MANTL, said: "What I think we're seeing is that many neobanks—Chime is a great example—have huge valuations, but their business is really built on interchange fees, which require scale. The interchange fee model works because we're in a bull market, with a lot of venture capital flowing into these companies and supporting them." According to The Information, Chime generated over $600 million in revenue from interchange fees in 2020. Harley noted that much of the venture capital is used for marketing and advertising to compete for market share from traditional institutions. He warned: "But what happens in an environment where venture capital dries up or the market underperforms? I do think that in 2021, some challenger banks will face a reckoning, some inflated valuations will come down, and their business models will be severely tested."
Aubrey Hawes, senior director of Oracle Financial Services Global Business Unit, said investors are chasing returns, and a large amount of venture capital is flowing into challenger banks. "You wonder how many will succeed. These venture firms are placing broad bets, and I don't think they expect all of them to hit."
A Thursday report from Axios found that challenger banks may also derive significant revenue from out-of-network ATM fees. According to data obtained by the outlet, 21% of Chime's revenue comes from fees when customers use out-of-network ATMs. Chime responded: "A small portion of our revenue comes from out-of-network ATM fees," adding that its customers have access to more than 38,000 free ATMs.
Challenger banks need to diversify
Martin said he expects more challenger banks to launch expanded products in 2021. "Challenger banks that gain momentum in the market will start to look more like traditional banks to capture more wallet share. Interestingly, fintech companies start out being different, but then they aspire to offer everything traditional banks currently provide."
Fintech company Upgrade launched a mobile banking platform this month to complement its existing personal loan and credit card products. Co-founder and CEO Renaud Laplanche said the new digital banking platform will not be a revenue driver but rather a tool to attract new customers to Upgrade's loan and credit card products. He said: "The mobile bank account is a way for us to provide more value to existing customers and acquire new ones."
Step, a challenger bank targeting Gen Z, plans to offer loans, and possibly investment and financial literacy products. CEO CJ MacDonald said: "An important part of our mission is financial literacy, so I think some educational tools can be built in." The San Francisco startup completed a $50 million Series B round in December 2020.
Subscription-based banking services
Although interchange fees remain a steady revenue source for most challenger banks, some niche fintech companies require monthly subscriptions or offer premium versions alongside free services. UK-based gohenry recently completed a $40 million funding round, which it plans to use for U.S. expansion, charging $3.99 per account per month in the U.S. The challenger bank provides prepaid debit cards and bank accounts for teenagers aged 6 to 18, with parental controls. CEO Alex Zivoder said subscriptions are the company's main revenue source. He told Banking Dive last December: "Interchange fees are certainly an additional factor, but the transaction volume of teenagers or children cannot compare to adults. It's hard to imagine a free model relying solely on interchange fees succeeding in our niche."
Azlo, which BBVA USA announced this month it would shut down, tested a subscription model last summer. In addition to free accounts, Azlo launched a $10-per-month subscription service bundling features like invoicing, and added automatic budgeting tools for payroll and taxes. CEO Cameron Peake told Banking Dive in September that the model was designed to be a revenue source beyond interchange fees. However, BBVA has announced it will close the platform before PNC acquires its U.S. operations.
Other challenger banks adopting subscriptions or premium services as additional revenue streams include Houston-based Majority (targeting the immigrant market), NorthOne (serving small businesses), and UK-based Revolut (which launched premium accounts in 2017).
Andrew Beatty, senior vice president and general manager of next-generation banking at FIS, said that as more challenger banks consider subscriptions or premium services to supplement interchange fee revenue, they should be aware that the transition is not easy. He said: "You can only offer premium services if you have quality products and services. When the competitive landscape is full of other paid services, moving from a lightweight product to charging is very difficult."
More niche banks
Many neobanks focus on specific populations to differentiate themselves from traditional institutions. Daylight launched in December 2020, specifically serving gay and transgender customers, offering LGBT financial planning advisors and allowing transgender individuals to use their preferred name rather than a "dead name" on cards. Majority targets immigrant communities by bundling digital banking, international calling, and remittance services. Remitly has targeted this group through remittance services and launched Passbook last year to offer banking services. Challenger banks like MoCaFi and Greenwood aim to serve Black and Brown communities.
Wole Coaxum, founder and CEO of MoCaFi, said: "Banks are fine, but they can't really solve these fundamental problems because it goes against their business model." He is committed to reducing the number of unbanked Black and Hispanic households in the U.S. Beatty said: "I think we'll see more challengers solving customer problems because that's what matters. I don't think we've reached a saturation point yet. There are certainly some good ideas emerging in fintech. Think about the challenges of the Paycheck Protection Program (PPP)—people moved quickly and created business opportunities. That clearly shows innovation can be very fast."
